By Felix Khanoba
Nigeria must achieve an average annual expansion of about 28 per cent in dollar terms to realise the Federal Government’s $1 trillion economy target by 2030, the First Deputy President of the Abuja Chamber of Commerce and Industry (ACCI), Prof. Adesoji Adesugba, has said.
Adesugba warned that although recent economic reforms had helped stabilise key macroeconomic indicators, the country needed stronger industrial growth, reliable electricity supply and increased foreign direct investment to translate the gains into sustainable economic expansion.
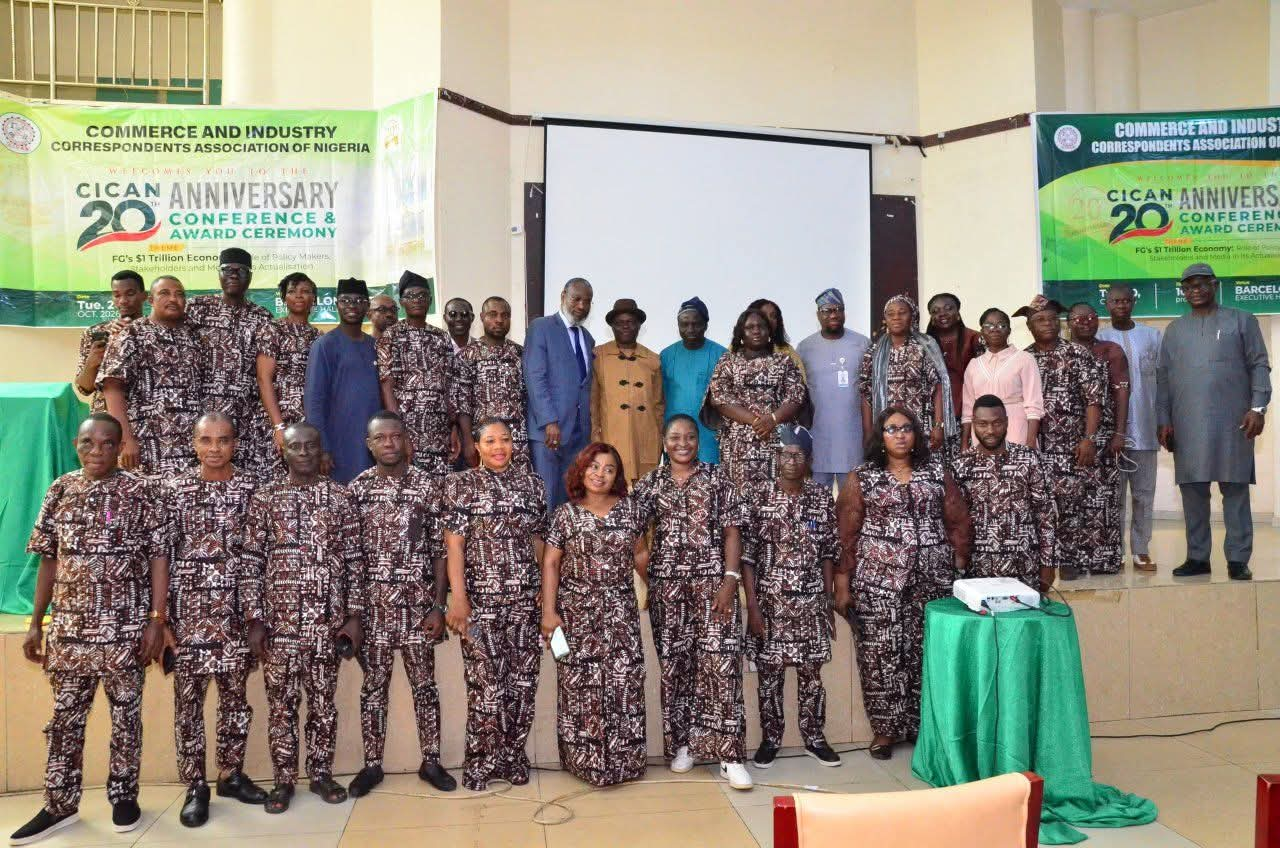
He spoke on Tuesday in Abuja while delivering the keynote address at the 20th anniversary lecture of the Commerce and Industry Correspondents Association of Nigeria (CICAN), with the theme, “Actualising the Federal Government’s $1 Trillion Economy: The Roles of Policymakers, Stakeholders and the Media.”
According to him, the $1 trillion ambition should be treated as a national mobilisation target rather than a guaranteed economic outcome, stressing that its actualisation would depend on the quality of policy implementation.
He said, “the $1 trillion economy is best understood not as a forecast but as a mobilisation target, and it will be won or lost on the quality of implementation rather than the quality of announcements.”
The former Managing Director of the Nigeria Export Processing Zones Authority acknowledged improvements in economic stability but argued that Nigeria had yet to achieve the scale of structural transformation required to meet the target.
“Stabilisation has been substantially achieved. Transformation has not yet begun at the scale the target requires,” he said.
Adesugba noted that Nigeria’s economy recorded real gross domestic product growth of 4.43 per cent in the second quarter of 2026, while first-half growth stood at 4.16 per cent, compared with 3.68 per cent in the corresponding period of 2025.
He also cited the decline in headline inflation to 14.63 per cent in September 2026 from 20.98 per cent a year earlier, alongside an increase in external reserves to $55.25bn, the highest level in 18 years.
However, he cautioned that these improvements had yet to translate into sufficient long-term investment in productive sectors.
According to him, capital importation reached $10.37bn in the first quarter of 2026, but foreign direct investment accounted for only $135.08m, representing 1.3 per cent of the total.
He explained that while portfolio investments could support currency stability, direct investments were more important for establishing factories, expanding production and creating jobs.
“Portfolio capital stabilises the currency; direct investment builds factories and jobs. We are attracting the former in abundance and the latter in trickles,” he said.
The ACCI official identified electricity supply as another major obstacle to the country’s economic ambitions, noting that Nigeria’s grid-connected power plants had an installed capacity of 13,625 megawatts, while average available capacity stood at 4,758MW in August 2026.
He argued that inadequate electricity supply continued to raise operating costs for businesses, undermine industrial productivity and discourage investment.
“No economy of 220 million people has ever approached a trillion dollars on five gigawatts of grid power,” he said.
Adesugba also raised concerns about the structure of economic growth, noting that services accounted for about 57 per cent of real output, while industrial growth slowed to 3.96 per cent in the second quarter of 2026 from 7.46 per cent a year earlier.
He said manufacturing growth of 3.24 per cent was encouraging but remained below the double-digit expansion historically associated with rapidly industrialising economies.
On the social implications of economic reforms, he cited World Bank estimates that 63 per cent of Nigerians, or about 140 million people, lived below the national poverty line in 2025.
He warned that persistent food inflation, which stood at 19.59 per cent in September 2026, continued to erode household purchasing power.
“A trillion-dollar economy that leaves the majority poor would be neither stable nor legitimate,” he said.
Speaking further, Adesugba said Nigeria’s current economic trajectory might deliver an economy worth about $450bn by 2030, with the $1 trillion mark reached around 2040 if existing growth patterns persisted.
Under a reform-acceleration scenario involving real economic growth of between six and seven per cent and a broadly stable naira, he projected that the economy could reach about $585bn by 2030 and attain the $1 trillion milestone around 2034.
A more optimistic scenario involving sustained high growth and real exchange-rate appreciation could produce an economy worth approximately $773bn by 2030, with the trillion-dollar target reached around 2032.
He cautioned against relying on exchange-rate appreciation alone to achieve the target, insisting that the expansion must be supported by increased domestic production and productivity.
“The exchange rate cannot do the heavy lifting,” he said, adding that an economy built on a strong naira but weak factories would amount to a statistical achievement rather than genuine economic transformation.
To strengthen accountability, Adesugba urged the government to establish measurable interim targets, including a $500bn economy, sustained real growth of at least six per cent, foreign direct investment exceeding 10 per cent of total capital importation, reliable electricity supply of at least 8,000MW and single-digit inflation.
He said such benchmarks would enable citizens, investors and journalists to assess progress towards the broader economic target.
“Milestones of this kind convert a slogan into a scorecard, and a scorecard is something that citizens, investors and journalists can hold the state accountable to,” he said.
Adesugba lists priorities for government, investors
The business leader called on federal and state governments to maintain policy consistency, strengthen fiscal and monetary coordination, improve electricity supply and create a more favourable environment for long-term investment.
He urged policymakers to sustain the current reform programme through the 2027 general election cycle, warning that policy reversals and fiscal indiscipline could undermine investor confidence.
He also called for improved implementation of the new tax laws, stronger statistical institutions and greater investment in technical education, research and innovation.
On investment promotion, Adesugba recommended repositioning Nigeria’s special economic zones and free trade zones as export-manufacturing and value-addition hubs linked to the African Continental Free Trade Area.
He said banks and other financial institutions should increase long-term lending to manufacturing, agriculture and infrastructure instead of concentrating excessively on government securities.
He further urged the organised private sector to support evidence-based policy advocacy, improve corporate governance and strengthen the integration of small and medium-sized enterprises into larger value chains.
According to him, universities and research institutions must align their work more closely with industrial needs, while businesses should be willing to fund and adopt locally developed innovations.
Adesugba also challenged business and economic journalists to go beyond reporting government announcements by explaining policies, verifying official claims, investigating public spending and tracking the impact of reforms on businesses and households.
He proposed that CICAN establish a quarterly $1 Trillion Tracker to monitor key indicators, including real GDP growth, the dollar value of the economy, foreign direct investment, electricity supply, inflation, manufacturing output, employment and poverty.
He said the initiative would provide an independent and transparent mechanism for assessing the country’s progress towards the economic target.
“I invite CICAN to consider establishing a quarterly CICAN $1 Trillion Tracker, an independent, transparent scorecard of the indicators that matter,” he said.
Earlier, CICAN Chairman, Gabriel Kuma, said the association’s 20th anniversary was an opportunity to reflect on two decades of professional commitment to reporting commerce, industry, investment and economic development.
Kuma said the association, registered in June 2006, had grown from a modest professional platform into an organisation seeking to deepen public understanding of economic policies and their implications for Nigerians.
He said reporting commerce and industry required more than announcing policy decisions or reproducing official statements.
“It demands understanding the connections between policies and people, between investments and jobs, between industrial production and national prosperity,” he said.
Kuma urged government agencies, businesses and development partners to strengthen their engagement with specialist journalists and support professional economic reporting.
He said the association remained committed to promoting informed, responsible and courageous journalism capable of contributing to national development.
The anniversary event attracted representatives of the Executive Vice Chairman of the Federal Competition and Consumer Protection Commission, the Executive Director of the Nigerian Export Promotion Council and the Director-General of the Small and Medium Enterprises Development Agency of Nigeria, among other stakeholders.
Adesugba and some heads of agencies under the Federal Ministry of Industry, Trade and Investment also received awards at the event.